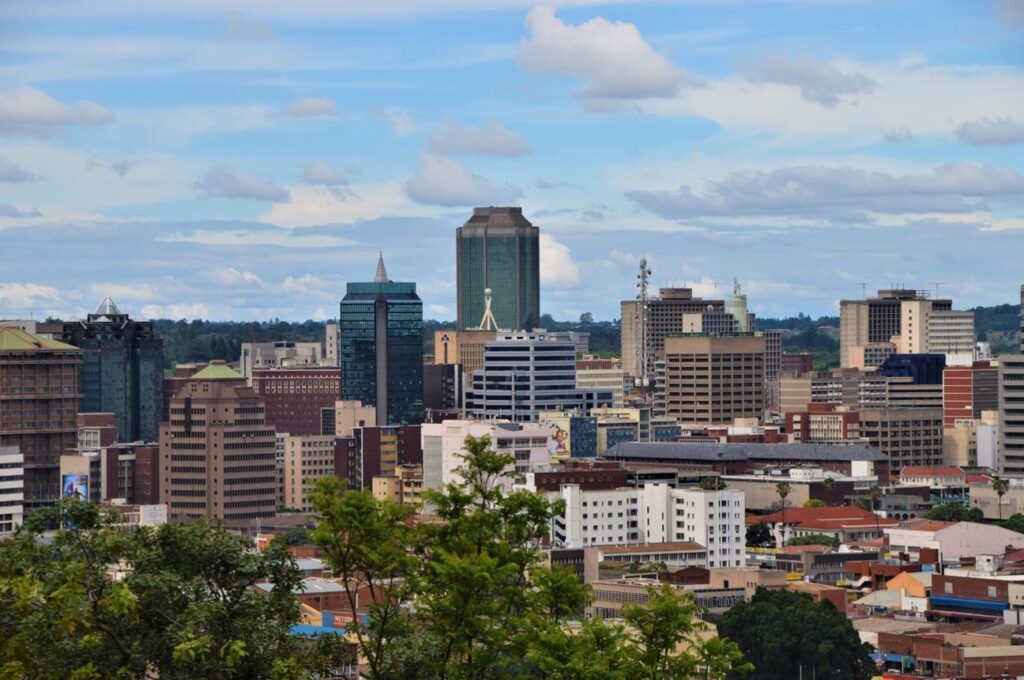
Zimbabwe is a fascinating—and painful—economic case because its collapse was not caused by one thing. It was a chain reaction: declining agricultural production, policy mistakes, loss of investor confidence, fiscal deficits, money creation, hyperinflation, currency collapse, debt default and years of institutional damage.
But there is an important twist: Zimbabwe’s economy in 2026 is in considerably better shape than the popular image of “Zimbabwe = hyperinflation.” It has actually achieved a degree of macroeconomic stabilization, although the underlying problems—especially debt, investment, productivity and trust in the currency—remain serious.
First, how did Zimbabwe get here?
1. Zimbabwe started from a relatively strong position
At independence in 1980, Zimbabwe inherited one of the more developed economies in sub-Saharan Africa.
It had:
- a relatively sophisticated manufacturing sector
- commercial agriculture
- significant mineral resources
- good infrastructure by regional standards
- relatively high education levels
- a functioning financial system
Agriculture was particularly important. Commercial farms produced tobacco, maize, wheat, beef and other products while supporting a substantial network of suppliers, processors and exporters.
So this wasn’t a country that was inherently poor or incapable of producing wealth.
The tragedy is that the productive base was progressively damaged.
2. The land reform programme became a major economic shock
This is one of the most politically sensitive parts of Zimbabwe’s story, so it is important to distinguish the objective from the economic consequences.
Zimbabwe had a profoundly unequal land distribution inherited from the colonial period. Correcting that imbalance was a legitimate political and social issue.
But beginning in the late 1990s and accelerating dramatically around 2000, the government’s Fast-Track Land Reform Programme involved the seizure and redistribution of large commercial farms, often without adequate compensation or a stable framework for new ownership.
The immediate economic problem wasn’t simply that farms changed hands.
It was that property rights became uncertain.
Farmers who had invested heavily in irrigation, machinery, livestock, soil management and processing infrastructure suddenly faced the possibility that their assets could be taken.
That affected investment far beyond agriculture.
The World Bank says the land reform disrupted agricultural output and weakened industries connected to agriculture, including input suppliers and food processing. It also contributed to perceptions of insecure property rights, capital flight and reduced foreign investment.
And agriculture isn’t an isolated industry.
Imagine a commercial farm producing wheat.
You have:
farmer → tractor dealer → fertilizer supplier → bank → transport company → mill → supermarket → exporter → government taxes
When agricultural production collapses, all those businesses feel it.
3. Then came the fiscal crisis
At the same time, government expenditure was becoming increasingly difficult to finance.
The government was spending more than it could sustainably raise through taxation and borrowing.
Eventually, the Reserve Bank of Zimbabwe became increasingly involved in financing government and quasi-government operations.
And this is where the situation became extremely dangerous.
If a government spends more money than it collects, it has several options:
- raise taxes
- cut spending
- borrow
- sell assets
- attract investment
- create money
Zimbabwe increasingly relied on the last option.
The IMF describes large quasi-fiscal operations by the Reserve Bank, including financing related to parastatals, agricultural programmes and other government-directed activities.
4. Then money printing met a shrinking economy
This is the classic recipe for monetary disaster.
Suppose an economy produces 100 loaves of bread and there is $100 circulating.
Very simplistically:
$1 → approximately one loaf
But imagine production falls to 50 loaves while the government creates another $200.
Now you have:
$300 chasing 50 loaves.
Prices rise.
The government creates more money to meet its obligations.
Prices rise further.
Workers demand higher wages.
Government expenditure increases.
More money is created.
Prices rise again.
And eventually people stop trusting the currency.
That’s essentially what happened—but on an extraordinary scale.
Zimbabwe’s inflation eventually became one of the most extreme episodes of hyperinflation in modern economic history.
The IMF estimates that inflation peaked at approximately 500 billion percent year-on-year in September 2008.
5. The Zimbabwe dollar effectively died
This produced one of the most extraordinary monetary situations the world has seen.
Prices were changing so rapidly that businesses could not meaningfully price goods.
People rushed to spend their money because holding it meant losing purchasing power.
Savings were destroyed.
Salaries became almost meaningless.
The banking system contracted dramatically.
Eventually, Zimbabweans essentially stopped using the domestic currency.
The government eventually accepted what was already happening:
Zimbabweans were using foreign currencies instead.
In 2009 Zimbabwe effectively abandoned the Zimbabwe dollar and adopted a multicurrency system dominated by the US dollar and South African rand. Hyperinflation immediately stopped because the government could no longer simply create unlimited Zimbabwe dollars.
And here’s the fascinating part:
Dollarization worked.
The economy began recovering.
Fiscal discipline improved dramatically.
The IMF notes that the budget deficit averaged roughly 2% of GDP between 2009 and 2015, compared with around 34% during 2004–08.
So Zimbabwe demonstrated something very important:
The economy wasn’t incapable of functioning. The monetary and institutional framework had become dysfunctional.
6. But Zimbabwe eventually made another huge mistake
The country didn’t remain completely dollarized forever.
By the middle of the 2010s, government finances were deteriorating again.
And Zimbabwe had an unusual problem.
It didn’t have enough US dollars.
So the government introduced monetary instruments that were supposed to function alongside the dollar.
One of the most famous was the bond note.
Eventually the system became extremely complicated:
- US dollars
- bond notes
- electronic bank balances
- mobile money
- foreign currencies
- unofficial exchange rates
People began discovering that one dollar in a bank wasn’t necessarily economically equivalent to one physical US dollar.
That destroyed confidence again.
The IMF says fiscal deficits increased substantially during 2016–18 and were financed partly through quasi-currency instruments issued at par with the US dollar and through the accumulation of external arrears.
7. Then Zimbabwe brought back a domestic currency
In 2019 the government reintroduced a domestic currency.
That was supposed to restore monetary sovereignty.
Instead, confidence problems returned.
The currency depreciated.
Inflation accelerated.
Then came another enormous shock:
COVID-19.
And after that, Zimbabwe experienced further currency instability.
Eventually the government introduced another currency:
The Zimbabwe Gold — ZiG
The ZiG was introduced in April 2024 and was designed to be backed by reserves including gold and foreign currency.
The basic idea was:
Don’t simply tell people the currency is valuable.
Instead:
Back it with tangible reserves and restrict monetary expansion.
Whether Zimbabwe can maintain that credibility over many years remains the big question.
So where is Zimbabwe TODAY?
This is where the story becomes surprisingly interesting.
Zimbabwe is not currently experiencing 2008-style hyperinflation.
In fact, the latest data show a considerable stabilization.
The World Bank reported that Zimbabwe’s economy grew by around 7.5% in 2025, following very weak growth in 2024, with agriculture and higher mining prices playing major roles. It also reported local-currency inflation of just 4.1% year-on-year in January 2026.
And the IMF is even more optimistic about the immediate picture.
Its July 2026 assessment says:
- GDP grew 8.3% in 2025
- 2026 growth is projected around 5%
- inflation is projected to average about 5.1%
- agriculture has rebounded
- mining remains strong
- gold prices are supporting exports
- the current account is expected to remain in surplus
- international reserves are increasing.
The World Bank’s newest report, published September 4, 2026, says local-currency inflation had returned to single digits in early 2026 for the first time since 1997, while GDP growth averaged almost 6% between 2021 and 2025.
That’s a remarkable turnaround from 2008.
But here’s the catch
Zimbabwe has stabilized without completely solving its economic problems.
Think of it like a patient who has finally stopped bleeding.
That’s extremely good news.
But the patient isn’t necessarily healthy.
The biggest problem is debt.
Zimbabwe has been effectively shut out of normal international capital markets for more than two decades because of arrears and debt problems.
The IMF says Zimbabwe has been in debt default and excluded from international capital markets and most official financing for more than 25 years.
The World Bank currently describes Zimbabwe’s external and overall public debt as unsustainable and in distress.
Public debt was approximately 45.6% of GDP in 2025.
That percentage might not sound catastrophic compared with countries carrying debt above 100% of GDP.
But debt isn’t just about the percentage.
You have to ask:
Can the country actually service the debt?
Zimbabwe’s problem is that it has accumulated enormous arrears and has limited access to cheap international financing.
And there’s another problem: TRUST
This may actually be Zimbabwe’s biggest economic problem.
Zimbabweans have lived through:
currency collapse → dollarization → bond notes → currency crisis → new currency → ZiG
People remember what happened to their savings.
Consequently, many Zimbabweans naturally prefer:
US dollars.
This creates a fascinating situation.
Zimbabwe wants a strong domestic currency because monetary sovereignty is useful.
But citizens want to protect their wealth.
So you get a battle between:
government monetary policy
and
public confidence.
The IMF still describes Zimbabwe as having a highly dollarized monetary system, low reserve buffers and a persistent gap between official and parallel exchange rates.
Mining is now extremely important
Zimbabwe has substantial mineral resources.
Gold is particularly important.
But the country also has:
- platinum
- lithium
- chrome
- diamonds
- nickel
- coal
This gives Zimbabwe a potential economic escape route.
The current recovery has benefited significantly from mining and high commodity prices.
And this is where Zimbabwe could potentially become a very different economy over the next decade.
Imagine if it successfully combines:
gold + lithium + platinum + agriculture + manufacturing + tourism + renewable energy
with credible property rights, predictable taxation and stable monetary policy.
The upside could be substantial.
The agricultural story is also changing
Agriculture remains one of Zimbabwe’s biggest potential engines.
The problem is that the land reform destroyed or weakened many of the old agricultural supply chains.
But production has been recovering in some areas.
The World Bank says the recent economic rebound has been helped by an agricultural recovery.
The challenge is climate.
Zimbabwe is extremely vulnerable to drought and weather shocks.
So a modern agricultural strategy would need:
- irrigation
- dams
- climate-resistant crops
- better financing
- improved seed and fertilizer systems
- modern farming technology
- secure land tenure
- stronger agricultural value chains
So was Zimbabwe “destroyed by sanctions”?
This needs a nuanced answer.
Sanctions contributed to Zimbabwe’s economic difficulties, but they don’t adequately explain the entire collapse.
Zimbabwe’s deterioration began alongside severe domestic policy problems, including agricultural disruption, fiscal deficits, monetary financing, governance problems and declining investor confidence.
The IMF explicitly links the economic decline to agricultural collapse, deteriorating international relations and expansionary fiscal/monetary policies.
At the same time, international isolation and sanctions did make financing, investment and economic recovery more difficult.
So the more accurate explanation is:
Domestic policy failures + agricultural disruption + monetary mismanagement + political/institutional problems + international isolation + debt accumulation.
Not simply:
“Sanctions destroyed Zimbabwe.”
And not simply:
“Mugabe destroyed Zimbabwe.”
The reality is more complicated.
The irony of Zimbabwe
This is perhaps the most interesting part.
Zimbabwe possesses many of the things economists normally associate with economic potential:
educated population + fertile land + minerals + tourism + relatively developed infrastructure + strategic location + entrepreneurial population.
The World Bank specifically points to Zimbabwe’s highly educated workforce and abundant natural resources as major assets.
Yet the country spent decades fighting something much harder to repair:
Economic credibility.
You can rebuild a road relatively quickly.
You can build a power plant.
You can open a mine.
But rebuilding trust in a currency, banking system, property rights and government institutions can take decades.
And Zimbabwe in 2026 is therefore a very interesting African economic experiment
The country has gone through almost the entire monetary cycle:
Strong economy
↓
Political/economic disruption
↓
Agricultural collapse
↓
Fiscal deficits
↓
Money creation
↓
Hyperinflation
↓
Currency death
↓
Dollarization
↓
Recovery
↓
Fiscal deterioration
↓
Currency crisis
↓
New currency
↓
ZiG
↓
Current stabilization
The latest numbers suggest that Zimbabwe has genuinely stabilized, rather than merely appearing stable. The IMF says its 2026 reform programme is meeting most targets, while the World Bank says macroeconomic stability has improved significantly.
But the country is not out of the woods.
Its biggest challenge now is turning stabilization into sustained prosperity—creating jobs, attracting long-term investment, resolving external arrears, improving productivity and convincing citizens that saving wealth in the domestic financial system is safe.
And that last part is crucial.
Zimbabwe doesn’t merely need a stable currency.
It needs Zimbabweans to believe that their money will still be worth something five, ten or twenty years from now.
That is a much harder achievement.
Never Miss a Story: Join Our Newsletter